

OneBlinc - Financial tools
OneBlinc
- 4.6
- 663.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
OneBlinc - Financial tools Pros and Cons
Pros
- Builds credit history through eligible recurring payments
- Offers flexible repayment options for short-term cash needs
- Provides clear account activity and repayment tracking
- Useful budgeting tools help monitor spending patterns
- Mobile-first design makes financial tasks quick to access
Cons
- Eligibility and available limits may vary by applicant
- Some features may require recurring membership or service fees
- Short repayment periods can make borrowing expensive if delayed
- Credit-building benefits depend on timely payments and reporting
- Not all financial tools may be available in every state
 Analysis by All-app
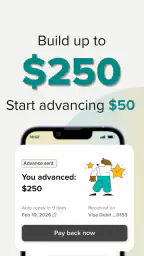
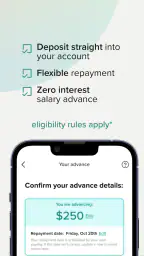
When a household budget gets tight between paydays, the difficult part is often not a large purchase. It is the small, unavoidable expense that arrives at the wrong moment: groceries, transport, a prescription, or a bill that cannot wait. I tested OneBlinc with that kind of situation in mind, and I found its purpose easy to understand. It is a finance app from OneBlinc that lets eligible users access part of their wages and send the money to a linked account. The central offer is access to up to 250 dollars, but the useful question is not simply how much it can provide. The real question is whether it fits the way you manage income, shared household responsibilities, and repayment pressure.
That distinction matters because this is not a general budgeting app, a shared family wallet, or a replacement for a bank account. I see it as a short-term cash-flow tool. Used carefully, it can help smooth an awkward gap. Used casually for regular spending, it can make the next payday feel even more restricted. My overall impression is positive for someone who understands that trade-off, but I would not recommend treating it like extra income.
How OneBlinc fits into a shared household
The most realistic household use is coordination rather than shared access. Imagine one person normally receives wages while another handles groceries or transport. A sudden expense appears, and the wage earner uses OneBlinc to access money and move it to the account they already use. The household can then decide together whether that money covers food, fuel, or a bill. The app may solve the timing problem, but it does not solve the communication problem.
I would keep the account firmly attached to the person whose wages are involved. Even when two adults share finances, I would not pass around login details or leave the app open on a communal phone. A linked bank account can expose sensitive financial information, and a shared device can blur who is making a decision. OneBlinc works best when one adult remains responsible for the account while the household discusses the result outside the app.
This is an important difference from a conventional joint banking arrangement. A joint account is designed around shared ownership and continuing access. OneBlinc is better understood as an individual wage-access tool that may support a household indirectly. If your main goal is to let several people view transactions, set spending limits, or manage a common balance, a bank account or dedicated household budgeting service will be a better match.
I also found that the app makes more sense when the household agrees on a specific purpose before anyone opens it. “We need money” is too vague. “We need to cover this week’s groceries and will reduce discretionary spending until payday” is a much safer decision. That simple conversation turns the app from an impulse button into a planned bridge.
Choose the account and device carefully
Setup begins with the linked account, so I would pay close attention to whose account is selected and whether it is the account used for everyday household expenses. Linking an account used by another family member could create confusion, especially if the wage earner and the person managing bills are different people. The cleanest arrangement is for the applicant to use an account they can monitor and explain.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
On a shared tablet or family phone, I would avoid saving sign-in details and would sign out after use if the device is regularly handled by other people. I would also avoid completing financial setup while distracted by children, visitors, or a busy kitchen. That sounds obvious, but small mistakes in account selection or transfer decisions are more likely when several people are watching or asking questions.
OneBlinc is free to install, which lowers the barrier to trying it, but “free” should not be confused with cost-free borrowing. The important financial questions are the ones shown during the actual request: what amount is available, when the money arrives, and what effect access will have on the next wage payment. I would read each screen rather than tapping through quickly, particularly if the household budget is already under pressure.
The app is available for devices running Android 7.0 or later. That makes it accessible on many older Android phones, which is useful for households that share an older spare device. Still, an older phone may have a smaller screen or slower performance, so I would complete setup on the device that receives account notifications and has current security updates whenever possible.
What to discuss before requesting money
A useful household routine is to agree on three points before making a request. First, name the expense. Second, decide who will monitor the linked account. Third, explain how the household will manage the reduced amount later. This takes only a few minutes, yet it prevents a common mistake: solving today’s problem while leaving tomorrow’s essential payment unfunded.
I would also write down the amount in a shared note, not because OneBlinc is a shared ledger, but because memory becomes unreliable when several people contribute to a budget. The note can include the purpose, the date of the request, and the person responsible for checking the account. Keep that record separate from login credentials. A household record should help with coordination, not give everyone access to private financial controls.
Another practical tip is to avoid making a request during an argument about money. If one person feels pressured to provide access or transfer funds immediately, the household boundary has already failed. The app should support a decision that both adults understand, not become a tool for persuading or monitoring another person.
Everyday use, timing, and trade-offs
In daily life, the strongest use case is a timing mismatch. A household may have enough income overall but still face several days when the account balance is low. In that situation, wage access can be more relevant than a traditional loan application, which may take longer and involve a larger commitment. The convenience is that the app is focused on connecting available wages with a linked account rather than asking the user to plan a long borrowing process.
That convenience has a limit. The app does not make the underlying expense disappear. If the same shortfall happens every pay cycle, repeated access could hide a structural budget problem. I would use the first request as a signal to review recurring bills, subscriptions, food costs, and payment dates. If the household needs the service constantly, a conversation with an employer, bank, credit counselor, or budgeting adviser may be more useful than another temporary advance.
Compared with an overdraft, OneBlinc may feel more deliberate because the user chooses to access wages instead of waiting for a transaction to push the account below zero. Compared with a credit card, it may be easier to connect the decision to earned income rather than an open revolving balance. However, neither comparison makes it automatically safer. The right choice depends on the terms shown at the moment of use and on whether the household can absorb the effect on future cash flow.
Compared with a standard budgeting app, OneBlinc serves a different need. A budgeting app helps you plan and observe money; this app is designed around access to wages. I would use a budget tracker alongside it if the household regularly loses visibility between paydays. Planning tools can reveal why the gap occurs, while OneBlinc may help with an immediate timing issue. Neither tool replaces the other.
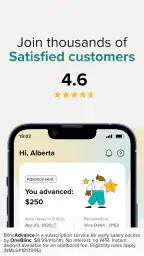
The app has a 4.6 average from around 4.8 thousand ratings, with more than 660 written reviews and over 100 thousand installs. Those figures suggest that many people have found the service worth trying, but they should not replace reading the terms of an individual request. A strong overall rating cannot tell you whether the timing, account arrangement, or repayment impact suits your household.
Boundaries for couples, roommates, and relatives
For couples, I would treat OneBlinc as belonging to the wage earner even if the money supports both people. That means the wage earner should approve the request, understand the consequences, and retain control of the account. The other partner can help decide the purpose and household plan, but shared responsibility does not require shared passwords.
For roommates, I would be more cautious. Roommates may share rent or groceries, but that does not automatically justify linking a shared account or using one person’s wage access for another person’s expense. If a roommate needs help, a clearly documented transfer between adults may be easier to understand than mixing wage access with informal household debts. The app is not a substitute for a roommate payment system.
For an adult child helping a parent, the same boundary applies. I would not install the app on a parent’s phone and manage it casually unless the financial arrangement is openly agreed and the adult account holder remains informed. A shared device can be convenient, but convenience should never remove the account holder’s understanding of what is being requested.
These boundaries are especially important because the service deals with real wages and a real linked account. A household can be emotionally close and still need separate financial identities. In my view, that separation is a strength, not a sign of mistrust. It makes responsibility clearer when the next payday arrives.
Age, trust, and the meaning of “Everyone”
OneBlinc carries an Everyone content rating, so its store presentation is suitable for a broad audience. That rating describes content suitability; it does not mean every person in a family should operate the financial account. I would keep use with the adult whose wages and linked account are involved, and I would explain the basic purpose to younger household members without giving them access to the account.
This matters in families where children use the same phone. A child might understand that the app provides money but not understand that the money is connected to earned wages and future household obligations. I would use a device lock, keep notifications private, and avoid leaving account screens visible. These are sensible precautions for any finance app, particularly one used around a shared device.
Trust also matters between adults. If one person is worried that another will request money without discussion, the solution is a household rule rather than silent surveillance. Agree on when the app may be used, what expenses qualify, and how the request will be recorded. If that agreement cannot be reached, I would not use OneBlinc as a workaround for a relationship or budgeting conflict.
The developer is OneBlinc, and the current version is 7.12.0. I would keep the app updated through the normal device store process and review the screens each time I use it, because financial workflows can change. I would not assume that a previous request works exactly like a future one. The safest habit is to verify the amount, destination, and timing every time.
Who should use it and who should skip it
I think OneBlinc is most suitable for a wage earner who has a temporary cash-flow gap, uses a personal or clearly understood linked account, and can explain how the next payday will cover remaining essentials. It can also suit a household that has agreed on a specific emergency expense and wants one person to manage the request while everyone understands the plan.
I would skip it if the household already struggles to pay necessities after every payday, if the requested money would cover nonessential impulse purchases, or if nobody knows how the next wage payment will be allocated. I would also avoid using it to lend money informally to friends or roommates. That creates a separate repayment problem and makes the original wage-access decision harder to track.
People looking for long-term credit, a joint spending account, automatic bill organization, investment tools, or detailed household analytics should choose a different type of financial product. OneBlinc’s appeal is its narrow focus. That focus is helpful when timing is the issue, but limiting when you want a complete money-management system.
Before confirming a request, I would ask myself whether the expense is essential, whether the linked account is the right one, and whether the household has a plan for the next pay cycle. I would also check the request details slowly and save a private record of what was chosen. Those steps are more valuable than trying to maximize the amount available.
My household verdict
After looking at OneBlinc through a shared-household lens, I see it as a practical but tightly bounded finance app. Its best role is to help one wage earner handle a short gap while keeping the household informed. It is not a family-control system, not a shared wallet, and not a replacement for planning. That clarity makes it easier to use responsibly.
The strongest way to use OneBlinc is as a planned bridge, never as a permanent extension of the household budget. Decide the purpose first, keep account access with the correct adult, protect the shared device, and check how the request affects the next payday. Those habits address the main risks without pretending that a financial app can solve every money problem.
The app is free and supports Android 7.0 and above, and its broad Everyone rating makes it approachable on a household device. Even so, I would treat it as an adult financial tool and keep private account activity private. The release date was February 18, 2025, so it is a relatively recent option, while the current version indicates that the product is actively presented in a modern release line.
My recommendation is therefore conditional but genuine: I would suggest OneBlinc to a person who needs short-term wage access, understands the effect on future cash flow, and can maintain clear household boundaries. I would not recommend it to someone seeking a complete budgeting solution or relying on repeated advances to make ordinary expenses work. For the right situation, it can reduce stress at an awkward moment. For the wrong situation, it can merely postpone the same pressure until payday.
Frequently Asked Questions
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help users manage short-term cash needs and everyday money matters from a mobile device. Depending on eligibility and location, its tools may include cash advances, budgeting features, spending insights, credit-building options, and access to a debit account or related services. Available features, limits, fees, and eligibility requirements can vary, so review the current terms before applying.
Who can use OneBlinc, and what are the eligibility requirements?
OneBlinc is generally intended for eligible adults who meet its identity, income, banking, and residency requirements. During registration, the app may ask you to provide personal information and securely connect a bank account or verify income. Approval is not guaranteed, and requirements can change over time. Users should also confirm that the service is available in their state or country before downloading.
Does OneBlinc charge fees or interest for its financial services?
The cost of using OneBlinc depends on the specific product and service you select. Some features may include membership charges, expedited transfer fees, optional services, or other costs, while a cash advance may have different pricing from a credit-building product. Carefully check the fee schedule, repayment terms, subscription details, and any applicable disclosures in the app before accepting an offer.
How does repayment work if I use a OneBlinc cash advance?
If you receive a cash advance through OneBlinc, repayment is typically scheduled for a future date connected to your income or bank-account activity. The app may use an authorized bank connection or another payment method to collect the amount due. Make sure sufficient funds are available, review the exact due date, and understand what may happen if repayment fails or is delayed.
Is OneBlinc safe to use, and what personal information does it require?
OneBlinc may request sensitive information such as your name, address, date of birth, employment or income details, identification data, and bank-account information to verify your identity and evaluate eligibility. Use the official app-store listing and review the privacy policy before registering. Enable device security, avoid sharing login details, and contact official support if you notice suspicious activity or an unfamiliar transaction.


